NHL Betting Bankroll Management
 Available in US
The difference between a bettor who survives a full NHL season and one who blows up by Christmas is not handicapping skill — it is bankroll management. You can identify edges, read analytics, and understand goaltender matchups at a deep level, but if you are staking 10% of your bankroll on every game, a four-game losing streak will leave you too crippled to capitalize on the edges that follow. Bankroll management is not the exciting part of betting. It is the part that keeps you alive long enough for the exciting parts to matter.
See also best NHL betting strategies for beginners.
Why Bankroll Management Matters in Hockey
The NHL regular season is 82 games per team, spread across roughly six months, with as many as 16 games on a single night. The volume of betting opportunities is enormous, and volume is both an advantage and a trap. It is an advantage because more games mean more chances to find value. It is a trap because more games mean more temptation to bet impulsively, to chase losses, and to overextend on a night when the board looks enticing.
Bankroll management imposes structure on this chaos. It defines how much you risk on each bet, how much of your total bankroll you are willing to lose before stepping back, and how you scale your wagers based on your confidence in the edge. Without this structure, every bet is an emotional decision, and emotional decisions compound into financial destruction over 1,300 games per season.
The math reinforces the point. Even a skilled bettor who wins 55% of their straight bets at -110 odds will experience losing streaks of eight to ten games during a full season. That is not a possibility — it is a statistical certainty. If your unit size is too large, those inevitable streaks will decimate your bankroll before the law of large numbers has a chance to work in your favor. Bankroll management is the mechanism that ensures you survive the downswings and remain positioned to profit from the upswings.
Unit Sizing: The Foundation
A unit is the standard amount you wager on a single bet. Most bankroll management systems define a unit as 1-3% of your total bankroll. If your bankroll is $1,000, a standard unit is $10 to $30. This sizing ensures that no single bet — win or lose — has a catastrophic impact on your overall position.
The conservative end of that range (1%) is appropriate for bettors who make a high volume of bets — five or more per day — because the aggregate exposure across many simultaneous wagers can add up quickly. If you are betting seven games on a Saturday night at 1% per bet, your total exposure is 7% of your bankroll, which is meaningful but manageable.
The aggressive end (3%) is appropriate for bettors who are selective and place one or two bets per day. With fewer concurrent bets, you can afford a larger unit size without overexposing your bankroll. The key is that your total exposure on any given day should not exceed 5-7% of your bankroll. Beyond that threshold, a bad night can set you back weeks.
Some bettors use a tiered system where the unit size varies based on confidence level. A standard bet gets one unit, a strong conviction play gets two units, and a rare premium pick gets three. This approach is fine in theory, but it requires honest self-assessment. If you find yourself assigning two or three units to most of your bets, you are not being selective — you are disguising overconfidence as a system.
Flat Betting vs. Variable Betting
Flat betting means wagering the same amount on every bet, regardless of the odds or the perceived edge. If your unit is $20, every bet is $20 — the heavy favorite, the underdog, the total, the prop. The simplicity is the strength. Flat betting removes the temptation to overbet on games you feel strongly about and underbet on games you are less sure of, which in practice eliminates a major source of bankroll erosion.
Variable betting, also called proportional or Kelly-based betting, adjusts the wager size based on the perceived edge and the odds. A bet with a larger estimated edge gets a bigger stake, and a bet with a smaller edge gets a smaller one. The Kelly Criterion is the most famous version of this approach, and it calculates the theoretically optimal bet size based on the probability of winning and the payout.
In theory, variable betting is mathematically superior to flat betting because it allocates more capital to your best opportunities. In practice, it is harder to execute because it requires accurate estimation of your edge — and most bettors overestimate their edge consistently. If your probability estimates are off by even a few percentage points, the Kelly formula tells you to bet too much, and the resulting overbetting does more damage than the theoretical optimization does good.
For most NHL bettors, flat betting is the safer and more practical choice. It is simple, it eliminates sizing errors, and it produces steady, predictable bankroll trajectories. Variable betting is a tool for experienced bettors who have a track record of accurate probability estimation and the discipline to bet smaller than the Kelly formula recommends.
Risk Management Over an 82-Game Season
The NHL season is a marathon, and your bankroll management must reflect that. A football bettor can survive with a bankroll sized for 17 games per team. A hockey bettor needs a bankroll that can absorb the variance of a 1,300-game season with multiple bets per night over six months. The runway must be long enough to survive the worst-case stretches without forcing you to reduce your unit size or stop betting entirely.
A common rule of thumb is to start the season with a bankroll equivalent to at least 50-100 units. If your unit is $20, your starting bankroll should be $1,000 to $2,000. This cushion ensures that a 15-unit drawdown — which is entirely normal for a bettor winning at 54% on straight bets — does not wipe out more than 15-30% of your bankroll. You remain fully operational, fully funded, and psychologically stable enough to stick with your process.
Drawdown limits are important psychological guardrails. Set a maximum drawdown threshold — say, 30% of your starting bankroll — at which you pause and review your approach. If you started with $1,500 and you are down to $1,050, stop betting for a week. Review your picks, check your process, and determine whether the losses are due to genuine errors in analysis or simply bad variance. If the process is sound, resume betting. If you find systematic mistakes, fix them before you put more money at risk.
Resist the urge to increase your unit size after a winning streak. The temptation is natural — you are up 20 units, you feel confident, and you want to capitalize on the momentum. But momentum is an illusion in a random process. The next 50 bets do not know or care about the previous 50. If you double your unit size after a hot streak and then hit an inevitable cold stretch, the losses hit twice as hard and erode the profit you built. Increase your unit size only when your total bankroll has grown meaningfully — 25-30% or more above your starting point — and increase it proportionally, not dramatically.
Tracking Your Results
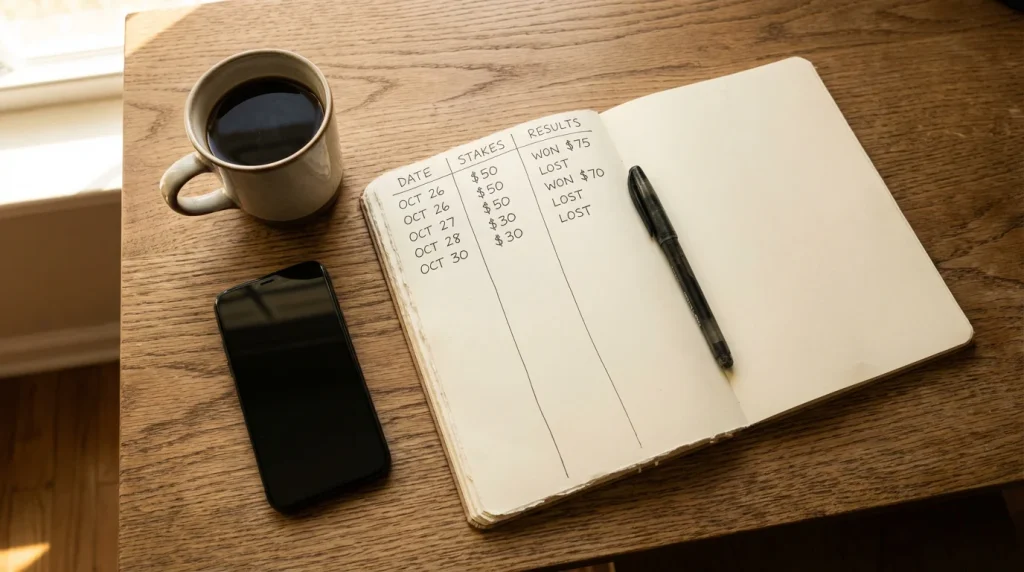
You cannot manage what you do not measure. Every bet you place should be logged in a spreadsheet or tracking tool that records the date, the game, the bet type, the odds, the stake, and the result. Over time, this record becomes the most valuable asset in your betting arsenal — not because it tells you what to bet next, but because it tells you what has worked and what has not.
Track your results by bet type. Are you profitable on moneylines but losing on totals? Are your player props carrying the portfolio while your puck line bets drag it down? This granularity reveals which markets are your strengths and which are liabilities. A bettor who discovers they are losing money on prop bets after 200 tracked wagers should either improve their prop analysis or stop betting props entirely. The data makes the decision obvious in a way that gut feeling never can.
Track by situation as well. Are you profitable when betting against teams on back-to-backs? Are your playoff bets outperforming your regular-season bets? Are you making money on home underdogs but losing on road favorites? These situational patterns help you refine your strategy and allocate more of your bankroll to the spots where your edge is strongest.
Review your tracking data at regular intervals — monthly or at natural season breaks like the All-Star break and the trade deadline. Look for trends, recalibrate your approach, and be honest about what the numbers say. The bettor who reviews and adapts is the one who improves. The one who bets blindly and hopes for the best is the one who donates to the sportsbook.
The Unglamorous Edge
Bankroll management will never produce a highlight-reel moment. No one tells stories about the night they bet 2% of their bankroll on a moderate underdog and won $30. The stories are always about the time someone parlayed four games and turned $50 into $800 — a story that omits the thirty times the same person lost $50 on the same kind of parlay.
The unsexy truth is that bankroll management is the single most reliable predictor of long-term betting success. Two bettors with identical handicapping ability will produce wildly different outcomes if one manages their bankroll with discipline and the other bets on impulse. The disciplined bettor grinds out small, consistent profits. The impulsive one swings between euphoria and despair, and over a full NHL season, the swings always favor the house.
Protect your bankroll the way a goaltender protects the net. Not every shot is dangerous, but the one you ignore is the one that beats you. Size your bets correctly, track your results honestly, and give yourself the runway to let the math work. The edge is in the process, and the process starts with not going broke.
NHL betting bankroll management at hockey betting.
